Learn how to apply for an instant loan online in India. Check eligibility, documents, the step-by-step process, interest rates, approval tips and repayment.
Not long ago, borrowing money meant taking a day off work, carrying a folder of photocopies to a branch, and waiting a week for someone to call back. That process has largely disappeared. Today you can apply for an instant loan online from your phone, complete verification digitally, and see the money credited to your bank account on the same day. The convenience is real, but so is the responsibility: an instant loan is still a debt with interest, charges and a repayment schedule. This guide walks you through exactly how to apply for an instant loan online, what lenders check, what it costs, and how to give your application the best possible chance of approval.
What Is an Instant Loan Online?
An instant loan online is an unsecured personal loan applied for and processed entirely over the internet. There is no collateral, no guarantor and no branch visit. Lenders use digital KYC, credit bureau data and automated underwriting to decide within minutes whether to approve you and on what terms. Loan amounts typically range from a few thousand rupees to several lakhs, with repayment tenures from three months to five years depending on the lender and your profile.
Because the loan is unsecured, the lender is relying on your creditworthiness alone. That is why your credit score, income stability and banking behaviour matter far more here than they would for a secured loan, and it is also why interest rates on instant loans sit higher than on home or car loans.
Why Borrowers Choose Instant Online Loans
- Speed: approval in minutes and disbursal often within hours, which matters in a medical emergency or an urgent repair.
- Paperless process: documents are uploaded or verified digitally through Aadhaar and account aggregator systems.
- Flexible end use: the money can go towards medical bills, education, travel, a wedding, debt consolidation or home renovation, with no restriction on purpose.
- Transparent comparison: rates, fees and EMIs are visible online before you commit to anything.
- Smaller ticket sizes: you can borrow only what you actually need instead of being pushed into a larger loan.
Eligibility Criteria for an Instant Loan Online
Criteria vary between lenders, but most Indian lenders look for broadly the same things:
- Age between 21 and 60 years at the time of application, with the loan maturing before retirement age.
- Indian citizenship with a valid PAN and Aadhaar.
- A regular income source, whether salaried employment, self-employment or a business.
- Minimum monthly income, commonly around ₹15,000 to ₹25,000 depending on your city and the lender.
- A credit score of 700 or above for the best pricing, though some lenders work with lower scores at higher rates.
- An active savings or current account in your own name, ideally the one your salary is credited to.
- A mobile number linked to your Aadhaar so that OTP based verification works.
Before you fill in a full application, use an online eligibility checker. These run a soft credit enquiry, which does not affect your score, and give you a realistic idea of the amount you qualify for.
Documents Required
Keep clear scans or photographs of the following ready so the application does not stall halfway through:
- Identity proof: PAN card, plus Aadhaar, passport, voter ID or driving licence.
- Address proof: Aadhaar, a utility bill, a rent agreement or passport.
- Income proof: the last three months of salary slips for salaried applicants, or the last two years of ITR and financials for self-employed applicants.
- Bank statements: usually the last three to six months, either uploaded as a PDF or fetched securely with your consent.
- A recent photograph, captured live during video or selfie KYC.
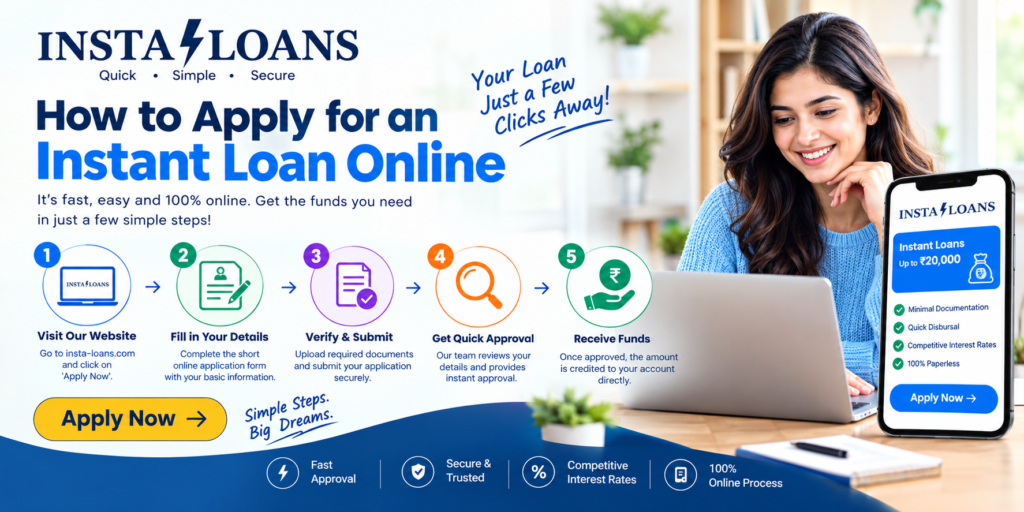
How to Apply for an Instant Loan Online: Step by Step
Step 1: Check your eligibility
Start on the lender’s website or app with the eligibility tool. Enter your age, city, monthly income and employment type. This takes under a minute and tells you whether it is worth proceeding, and roughly how much you can borrow.
Step 2: Decide the amount and tenure
Borrow what you need, not what you are offered. Use an EMI calculator to test different combinations. A longer tenure lowers the EMI but raises the total interest paid; a shorter tenure costs less overall but strains your monthly cash flow. As a rule of thumb, keep all your EMIs together below 40 to 50 percent of your take-home pay.
Step 3: Fill in the application form
Enter your personal, employment and income details exactly as they appear on your documents. Mismatched spellings, an outdated address or a wrong employer name are among the most common reasons applications get delayed or rejected. Double-check your PAN and mobile number before you submit.
Step 4: Complete KYC verification
Most lenders offer Aadhaar OTP based e-KYC, which is instant. Some require a short video KYC call where an agent asks you to show your PAN and confirm a few details. Sit somewhere well lit with a stable internet connection and keep the original documents in hand.
Step 5: Share income and bank details
Upload salary slips and bank statements, or authorise the lender to fetch your statement through a regulated account aggregator. The second route is faster and reduces the chance of a document being rejected for poor image quality. Never share your net banking password with anyone; legitimate lenders do not ask for it.
Step 6: Review the loan offer carefully
Once underwriting is complete you will receive an offer showing the sanctioned amount, interest rate, processing fee, EMI, tenure and total repayment. Read the key fact statement, which lenders regulated by the Reserve Bank of India are required to provide. Pay attention to the annual percentage rate rather than just the headline interest rate, since the APR includes fees and shows you the true cost.
Step 7: E-sign and receive disbursal
Accept the offer, sign the agreement digitally with an Aadhaar based e-signature, and set up an auto-debit or NACH mandate for your EMIs. The money is then transferred to your bank account, usually within a few minutes to 24 hours. Download and save the signed agreement and repayment schedule for your records.
Interest Rates, Fees and Charges
Interest on instant personal loans in India typically ranges from around 10.5 percent to 30 percent a year, depending on your credit profile, income and the lender. Beyond interest, expect some or all of the following:
- A processing fee, commonly 1 to 3 percent of the loan amount, plus GST.
- Stamp duty or documentation charges as applicable in your state.
- Late payment penalties and bounce charges if an EMI fails.
- Foreclosure or part-prepayment charges, often after a lock-in of a few EMIs.
Add these up before you compare two offers. A loan with a slightly lower rate but a heavy processing fee can work out more expensive than one with a higher rate and no fee.
Tips to Improve Your Chances of Approval
- Check your credit report for errors before applying and get any wrong entries corrected.
- Clear outstanding credit card dues or small overdue amounts, which weigh heavily on your score.
- Apply to one or two lenders at a time. Multiple simultaneous applications create several hard enquiries and signal credit hunger.
- Show a stable income: at least six months in your current job, or two years in your business, helps considerably.
- Keep your bank account healthy, with no cheque bounces or frequent low balances in the months before you apply.
- Consider a smaller amount first. Repaying it on time builds a record that unlocks larger loans later.
Mistakes to Avoid
The fastest way to turn a convenient loan into an expensive one is to skip the fine print. Do not accept an offer without reading the charges, and do not borrow to repay another loan without a clear plan. Be wary of any app or website that asks for a fee before disbursal, demands access to your contacts and photo gallery, or cannot tell you which RBI regulated bank or NBFC is actually lending the money. Genuine lenders publish their partner details, their grievance redressal officer and a working customer support channel.
Repaying Your Instant Loan
Repayment is usually through an auto-debit mandate on your EMI date. Keep enough balance in the account two days before that date to avoid a bounce. If your income improves, part-prepayment can cut your interest burden considerably. If you expect to miss an EMI, contact the lender before the due date; a restructured schedule is far better for your credit report than a default. Every EMI paid on time adds to your score and makes the next loan cheaper.
Final Thoughts
Applying for an instant loan online is genuinely simple: check eligibility, pick a sensible amount, submit accurate details, complete digital KYC, review the offer and sign. The part that deserves your time is not the application but the decision behind it. Borrow for a purpose you can justify, choose an EMI that fits comfortably in your monthly budget, and read the cost of the loan in full before you accept. Done that way, an instant loan is a useful financial tool rather than a burden.
At Insta Loans, the application takes only a few minutes and the terms are shown to you upfront, so you always know exactly what you are signing up for.
Frequently Asked Questions
1. How long does it take to get an instant loan online?
For a complete application with clean documents, approval usually takes a few minutes and disbursal happens within a few minutes to 24 hours. Applications that need manual review, additional income proof or address verification can take one to two working days.
2. What documents do I need to apply for an instant loan online?
You generally need a PAN card, Aadhaar linked to your mobile number, address proof, the last three to six months of bank statements, and salary slips or ITR if you are self-employed. Everything is uploaded digitally, so no physical paperwork is required.
3. What credit score is needed for an instant loan online?
Most lenders prefer a score of 700 and above for the best rates. Some lenders approve applicants in the 600 to 700 range at a higher interest rate or a smaller loan amount, and a few consider new-to-credit borrowers using income and banking behaviour instead.
4. Can I apply for an instant loan online without a salary slip?
Yes. If you are self-employed or paid in cash, lenders can assess you using bank statements, ITR filings, GST returns or business receipts. The loan amount offered may be lower until your income pattern is established.
5. Does applying for an instant loan online affect my credit score?
Checking your own eligibility is a soft enquiry and does not affect your score. Submitting a full application triggers a hard enquiry, which can reduce your score slightly. Several applications in a short period have a larger effect, so apply selectively.
6. Are there charges apart from interest on an instant loan?
Yes. Common charges include a processing fee, GST on fees, stamp duty or documentation charges, late payment penalties, bounce charges and sometimes a foreclosure fee. Always read the key fact statement to see the full cost of borrowing.
7. Can I repay an instant loan before the tenure ends?
Most lenders allow part-prepayment or full foreclosure after a minimum number of EMIs. Some charge a foreclosure fee on the outstanding principal, so confirm the lock-in period and the fee before you plan an early closure.
8. How do I know an online loan provider is genuine?
A genuine lender is an RBI regulated bank or NBFC, or works with one, and displays that partnership clearly. It never asks for an advance fee before disbursal, shares a written sanction letter and key fact statement, and uses a secure website with published contact and grievance details.