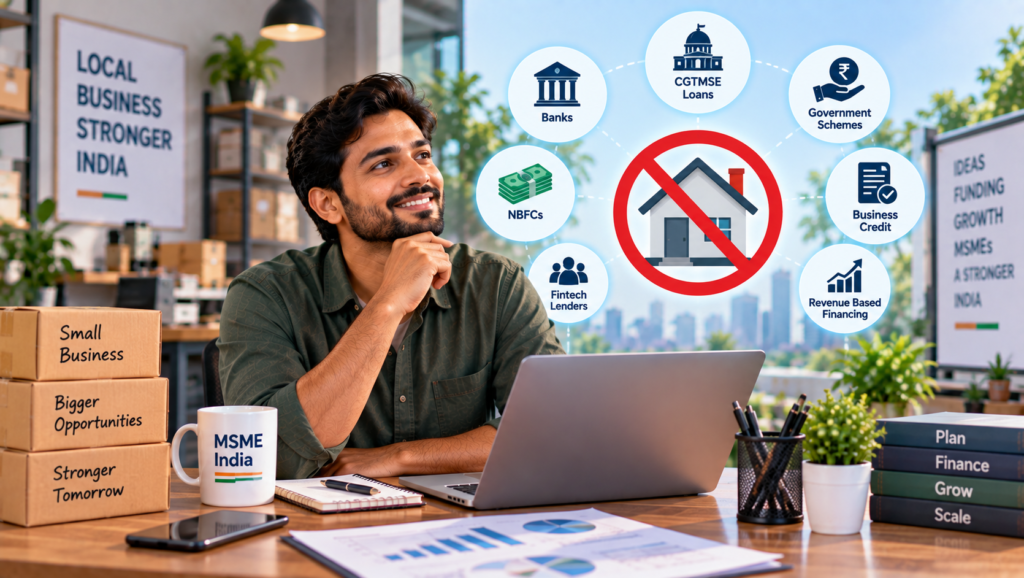
MSMEs can explore unsecured business loans, CGTMSE-backed financing, and other funding options when they need business finance without pledging property or other collateral.
Many small businesses need funding to purchase inventory, manage cash flow, hire employees, buy equipment, or expand into new markets. But not every business owner has property or other valuable assets to pledge against a loan.
A business loan without collateral can be an option for eligible MSMEs that need financing without offering traditional security such as property. These loans are generally assessed using factors such as credit history, business revenue, banking activity, repayment capacity, and business vintage.
If you are looking for a collateral free business loan, there are several routes worth exploring in India.
What Is a Business Loan Without Collateral?
A business loan without collateral is financing where the borrower does not pledge a specific asset, such as residential property or commercial property, as security for the loan.
These loans are also commonly called unsecured business loans.
Because the lender does not have a specific asset to recover if the borrower defaults, the lender may assess the business and borrower more carefully. Depending on the lender and product, factors can include:
- Credit history
- Business turnover
- Bank account activity
- Business vintage
- Income and cash flow
- Existing liabilities
- GST or tax records
- Repayment capacity
The exact eligibility criteria and loan terms vary between lenders.
7 Ways to Get a Business Loan Without Collateral
1. Apply for an Unsecured Business Loan
An unsecured business loan India option may be available from banks, NBFCs, and other regulated lenders.
Since no traditional property collateral is required, lenders may rely more heavily on the applicant’s financial profile.
These loans may be useful for expenses such as:
- Working capital
- Inventory purchases
- Marketing
- Business expansion
- Office expenses
- Equipment purchases
Before applying, compare the interest rate, processing fee, repayment tenure, foreclosure conditions, and other applicable charges.
2. Explore Government-Backed MSME Financing
Government-supported credit programmes can provide financing opportunities for eligible small businesses.
Some schemes are designed to improve access to institutional credit for micro and small enterprises. Eligibility, loan limits, guarantee conditions, and lender requirements vary by scheme.
Business owners should check the current official scheme guidelines rather than relying on old information found online.
3. Consider CGTMSE-Backed Credit
CGTMSE business loan financing can be relevant for eligible micro and small enterprises that require credit without conventional collateral.
The Credit Guarantee Fund Trust for Micro and Small Enterprises, or CGTMSE, provides credit guarantee support to eligible lenders for qualifying credit facilities extended to eligible MSEs.
The important point is that CGTMSE does not simply mean that every business can directly apply for a “CGTMSE loan.” The credit facility is provided by eligible lending institutions, and the lender evaluates the borrower’s eligibility and loan application.
The guarantee mechanism is intended to support access to credit where conventional collateral or third-party guarantees may not otherwise be available.
Always check the latest CGTMSE guidelines and participating lender requirements before applying.
4. Use Digital or Cash-Flow-Based Business Financing
Some lenders use digital financial information and business cash-flow data as part of their credit assessment.
For businesses that receive regular payments through bank accounts or digital channels, transaction history may help demonstrate business activity and repayment capacity.
Depending on the lender, the assessment may consider:
- Bank transactions
- Sales information
- GST data
- Business revenue
- Existing liabilities
- Account activity
This can be particularly relevant for businesses that do not have property available for security.
However, approval is never automatic, and the lender’s own underwriting criteria still apply.
5. Consider Equipment Financing
If your main requirement is to purchase machinery, computers, vehicles, or other business equipment, a general business loan may not be the only option.
Equipment financing is designed specifically for purchasing business assets.
Depending on the financing structure, the equipment itself may form part of the security arrangement. This can be different from taking a conventional loan against property.
For an MSME purchasing equipment for expansion, comparing equipment finance with an unsecured working-capital loan can help identify the financing structure that fits the requirement.
6. Look at Business Credit Lines and Working Capital Facilities
Businesses with recurring short-term funding requirements may consider working-capital facilities or business credit lines.
Instead of borrowing a large amount for a single long-term requirement, a suitable credit facility can help manage temporary cash-flow gaps.
For example, a business may need additional funds to purchase inventory before receiving payments from customers.
The cost and structure of these facilities vary. Check interest calculations, renewal conditions, fees, repayment requirements, and the lender’s eligibility criteria.
7. Build Eligibility for Future Collateral-Free Funding
Sometimes the most useful step is to strengthen your financial profile before applying for a larger loan.
If your business is relatively new or has limited financial history, improving its documentation and banking records can help create a clearer picture of business performance.
Focus on:
- Maintaining proper business accounts
- Filing applicable tax returns on time
- Keeping GST records organised
- Monitoring business cash flow
- Paying existing EMIs on time
- Separating personal and business transactions
- Maintaining accurate financial statements
A stronger financial record can make future financing applications easier to evaluate.
Who Can Apply for an MSME Loan Without Security?
Eligibility depends on the specific lender or scheme, but businesses that may seek MSME loan without security financing include:
- Sole proprietorships
- Partnerships
- Private limited companies
- Limited liability partnerships
- Eligible micro and small enterprises
- Manufacturing businesses
- Trading businesses
- Service businesses
The business may need to meet requirements related to turnover, vintage, credit history, registration, financial performance, and repayment capacity.
Having MSME or Udyam registration can be relevant for certain government-backed schemes, but registration alone does not guarantee loan approval.
Documents You May Need
For a business loan without property, lenders may request documents such as:
- PAN and identity documents
- Address proof
- Business registration documents
- Udyam registration, where applicable
- GST registration and returns, where applicable
- Bank statements
- Income tax returns
- Financial statements
- Details of existing loans
- Business address proof
- Ownership or partnership documents
The exact documentation varies by lender and loan type.
Business Loan Without Property: What Should You Check?
Before accepting an unsecured loan, do not look only at the advertised interest rate.
Compare:
| Factor | Why It Matters |
|---|---|
| Interest rate | Determines borrowing cost |
| Processing fee | Adds to the initial cost |
| Loan tenure | Affects monthly repayment |
| EMI | Shows regular cash-flow requirement |
| Prepayment terms | Important if you want to repay early |
| Late-payment charges | Can increase borrowing costs |
| Loan amount | Should match your actual requirement |
| Eligibility | Determines whether you can qualify |
A loan without collateral may reduce the need to pledge property, but it does not mean the borrowing is risk-free.
Is a Collateral-Free Business Loan Right for Your MSME?
A collateral free business loan can be useful when an eligible business needs funding but does not want to pledge property or another major asset.
However, unsecured financing can come with different pricing and eligibility requirements compared with secured loans.
Before applying, consider:
- How much funding does the business actually need?
- Can monthly cash flow support the repayment?
- What is the total cost of borrowing?
- Are there processing or other fees?
- Is a government-backed credit guarantee route available?
- Would equipment finance or working-capital funding be more appropriate?
Answering these questions can help you choose a financing structure based on your business requirement rather than simply choosing the easiest application.
Final Takeaway
A business loan without collateral can give eligible MSMEs access to funding without requiring traditional property security. Depending on your business profile, options can include unsecured business loans, government-supported MSME financing, CGTMSE-backed credit, cash-flow-based lending, equipment financing, and working-capital facilities.
However, every funding route has its own eligibility criteria, costs, documentation requirements, and repayment conditions.
If you need an MSME loan without security, compare the total borrowing cost and repayment requirements carefully. A collateral-free loan can solve a funding gap, but the EMI or repayment obligation still needs to fit comfortably within your business’s cash flow.
FAQs
Can I get a business loan without collateral in India?
Yes, eligible businesses may be able to obtain unsecured business financing from banks, NBFCs, and other regulated lenders. Eligibility depends on factors such as credit history, business performance, turnover, vintage, and repayment capacity.
What is a collateral-free business loan?
A collateral-free business loan does not require the borrower to pledge a specific asset such as property as security. It is generally assessed using the borrower’s financial and business profile.
What is a CGTMSE business loan?
A CGTMSE-supported credit facility uses a credit guarantee mechanism for eligible credit facilities provided by participating lenders to eligible micro and small enterprises. It does not mean that every business automatically qualifies for financing.
Can MSMEs get loans without property?
Yes. Depending on eligibility, MSMEs may access unsecured business loans, government-supported credit, CGTMSE-backed facilities, working-capital products, and other financing options that do not require traditional property collateral.
Is an unsecured business loan more expensive?
The cost depends on the lender, borrower profile, loan amount, tenure, and other terms. Since unsecured financing does not rely on traditional collateral, borrowers should compare the total cost rather than looking only at the advertised interest rate.
What documents are required for an MSME loan without security?
Depending on the lender, documents may include identity proof, business registration, bank statements, GST records, income tax returns, financial statements, Udyam registration, and details of existing financial obligations.
Does Udyam registration guarantee a business loan?
No. Udyam registration can be relevant for MSME-related schemes and benefits, but it does not by itself guarantee loan approval. The lender’s eligibility and credit assessment still apply.