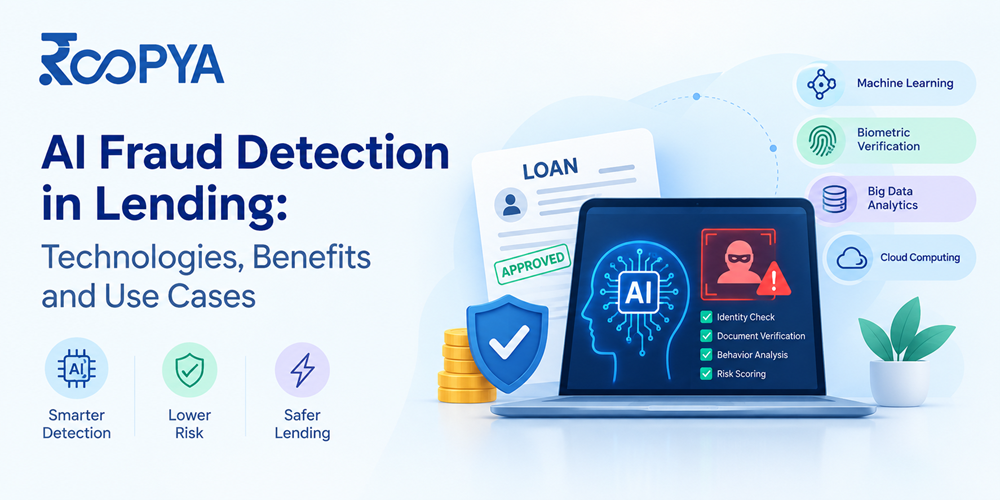
Discover how AI fraud detection is transforming lending — key technologies, benefits, and real-world use cases for banks and NBFCs. Learn more with Roopya.
Lending fraud is no longer a fringe risk that credit teams handle with a checklist and a watchful eye. As banks and NBFCs push more of their loan origination and disbursement online, fraudsters have moved just as fast — using stolen identities, forged documents, synthetic profiles, and coordinated “fraud rings” to exploit gaps in traditional underwriting. The result is a problem that grows in both scale and sophistication every year, and one that rule-based systems built for a paper-driven era were never designed to catch.
Artificial intelligence has changed what is possible. Instead of relying only on static rules — “flag any loan above X amount” or “reject if PAN and Aadhaar don’t match” — AI-powered fraud detection systems learn from millions of data points, adapt to new fraud patterns as they emerge, and evaluate risk in real time, often within seconds of a loan application being submitted. For lenders running a modern Loan Management System (LMS) or Loan Origination System (LOS), embedding AI fraud detection into the workflow is quickly becoming table stakes rather than a competitive edge.
This guide walks through the core technologies behind AI fraud detection in lending, the concrete benefits lenders can expect, and the use cases where AI is already proving its worth — from identity verification to post-disbursement monitoring.
The Rising Cost of Fraud in Digital Lending
Digital lending has made credit faster and more accessible, but it has also expanded the attack surface for fraud. Application volumes have grown dramatically as banks, NBFCs, and fintech lenders offer instant personal loans, embedded credit, and buy-now-pay-later products — often with minimal human touchpoints. Every one of those digital touchpoints is a potential entry point for a bad actor.
Fraud in lending typically falls into a few broad categories: first-party fraud, where a genuine borrower misrepresents their identity or intentions and has no plan to repay; third-party or identity fraud, where a fraudster uses someone else’s identity (often stolen KYC documents) to obtain a loan; synthetic identity fraud, where fabricated identities are built by blending real and fake data to pass verification checks; and organized fraud rings, where multiple coordinated applications are used to exploit underwriting weaknesses at scale, sometimes referred to as “bust-out” fraud.
The cost of this fraud isn’t limited to the principal amount lost. Lenders also absorb the cost of collections efforts that go nowhere, regulatory scrutiny, reputational damage, and the operational burden of manually reviewing flagged cases. As loan books scale, manual review simply cannot keep pace — which is exactly the gap AI is built to close.
Why Traditional Fraud Detection Falls Short
Rule-based fraud detection systems work by applying a fixed set of “if-this-then-that” conditions: flag applications with mismatched addresses, reject multiple applications from the same device within 24 hours, or escalate loans above a certain ticket size for manual review. These rules are easy to understand and simple to implement, which is why they remain common in legacy lending systems.
The problem is that rules are static, while fraud is dynamic. Fraudsters study the rules lenders use — often through trial and error — and adjust their tactics to stay just under the threshold. A rule that catches yesterday’s fraud pattern does little against tomorrow’s. Rule-based systems also tend to generate a high volume of false positives, flagging genuine borrowers as suspicious simply because their profile doesn’t fit a narrow set of conditions. This creates friction for good customers and wastes analyst time chasing dead ends.
Perhaps most importantly, rule-based systems struggle to connect the dots across data points. A single suspicious phone number or IP address might not trigger any individual rule, but when combined with a slightly unusual income pattern, a newly issued document, and an address shared with three other recent applicants, the picture changes entirely. Spotting that kind of pattern requires a system that can weigh many weak signals together — which is precisely what machine learning does well and static rules do not.
What Is AI-Powered Fraud Detection?
AI-powered fraud detection uses machine learning, deep learning, and related techniques to analyze borrower data — application details, documents, device and behavioral signals, credit bureau data, and transaction history — and produce a real-time risk score or fraud probability for every loan application or account event. Rather than following fixed rules, these models are trained on historical data (both fraudulent and legitimate cases) and learn the subtle combinations of features that correlate with fraud.
Crucially, AI systems can continue to learn as new data comes in. When a new fraud pattern emerges and is confirmed, that information can be fed back into the model, improving its ability to detect similar attempts in the future. This adaptive quality is what allows AI-based systems to keep pace with fraudsters who are constantly refining their methods.
Core Technologies Powering AI Fraud Detection
A modern AI fraud detection stack for lending typically combines several complementary technologies, each suited to a different part of the fraud problem.
Machine Learning Classification Models
Supervised learning models — such as gradient-boosted trees, random forests, and logistic regression — are trained on labeled historical data to classify new applications as low, medium, or high fraud risk. These models excel at combining dozens or hundreds of variables (income, employment type, loan amount, bureau score, application timing, and more) into a single, actionable risk score that can be embedded directly into loan origination workflows.
Deep Learning and Neural Networks
For more complex patterns — particularly across large volumes of unstructured or sequential data, such as transaction histories or clickstream behavior — deep learning models can detect subtle, non-linear relationships that simpler models miss. Neural networks are especially useful for identifying synthetic identities, where individual data points may look legitimate but the overall pattern is fabricated.
Natural Language Processing (NLP)
NLP techniques analyze free-text fields, self-employment declarations, chat transcripts, and even the wording of loan purpose statements to detect inconsistencies or language patterns associated with fraudulent intent. NLP is also used to cross-check details across documents — for instance, verifying that an employer name and address are consistent across a salary slip, bank statement, and application form.
Computer Vision and Document Forensics
Computer vision models, combined with optical character recognition (OCR), examine uploaded KYC documents — Aadhaar, PAN, salary slips, bank statements — for signs of tampering: inconsistent fonts, misaligned text, digital editing artifacts, or mismatched metadata. This is one of the highest-impact applications of AI in lending, since document forgery is one of the most common entry points for fraud.
Graph and Network Analytics
Fraud rarely happens in isolation. Graph-based analysis maps relationships between applicants, devices, phone numbers, addresses, and bank accounts to surface hidden connections — such as ten “unrelated” applicants sharing the same device fingerprint or referral code. This technique is particularly effective against organized fraud rings that rule-based systems and simple ML models routinely miss.
Behavioral Biometrics
By analyzing how a user interacts with a digital application — typing rhythm, mouse movement, scroll speed, time spent on each field — behavioral biometrics can distinguish genuine applicants from bots, automated scripts, or someone filling out a form on another person’s behalf. This adds a layer of fraud detection that operates independently of the data entered.
Anomaly Detection (Unsupervised Learning)
Not all fraud looks like fraud the system has seen before. Unsupervised anomaly detection models establish a baseline of “normal” applicant or account behavior and flag statistically unusual deviations, even without prior labeled examples. This is essential for catching novel fraud patterns that supervised models — trained only on known fraud types — would otherwise miss.
Ensemble Models and Explainable AI (XAI)
In practice, most production fraud systems combine multiple models into an ensemble, weighing outputs from several techniques to arrive at a final decision. Given the regulatory environment lenders operate in, explainability tools (such as SHAP or LIME) are increasingly built alongside these models so that every flagged decision can be traced back to the specific factors that drove it — a requirement for both internal audit and regulatory compliance.
Key Benefits of AI Fraud Detection in Lending
Real-Time Risk Assessment
AI models can score an application in milliseconds, allowing lenders to approve genuine borrowers instantly while routing suspicious applications for review — without slowing down the overall lending funnel.
Fewer False Positives, Better Customer Experience
Because AI models weigh many signals together rather than triggering on a single rule, they are far more precise at distinguishing genuine outliers from actual fraud. This reduces the number of legitimate customers who are wrongly declined or delayed, improving conversion rates and customer satisfaction.
Lower Operational Costs
Automating the bulk of fraud screening reduces the manual review workload on credit and risk teams, letting analysts focus their time on the small subset of genuinely ambiguous cases rather than reviewing every application by hand.
Adaptability to New Fraud Patterns
Because AI models retrain on new data, they can adapt to emerging fraud tactics far faster than a team manually rewriting rules — an important advantage as fraud techniques evolve alongside technology like generative AI and deepfakes.
Scalability Across Loan Products and Volumes
As a lender’s book grows — across personal loans, business loans, BNPL, or secured lending — AI systems scale without a proportional increase in headcount, making them well suited to high-growth digital lenders and NBFCs.
Stronger Regulatory Compliance
With explainable AI techniques and detailed audit trails, lenders can demonstrate to regulators exactly why an application was flagged or declined, supporting compliance with KYC, AML, and fair-lending requirements.
Reduced Credit Losses
By catching fraud earlier in the funnel — ideally before disbursement — lenders avoid the far higher cost of chasing recoveries or writing off loans that were fraudulent from the start.
Real-World Use Cases of AI Fraud Detection in Lending
Identity and Synthetic Identity Verification
AI cross-references applicant data against government ID databases, credit bureaus, and third-party data sources in real time, while machine learning models flag synthetic identities built from a mix of real and fabricated information — a fraud type that has grown rapidly as static KYC checks alone have become easier to circumvent.
Document Forgery Detection
Computer vision and OCR-based models scan uploaded salary slips, bank statements, PAN cards, and Aadhaar documents for tampering, inconsistent formatting, or signs of digital editing, catching forged documents that would pass a quick manual glance.
Income and Employment Fraud
AI models cross-check declared income, employer details, and bank statement patterns against typical salary deposit behavior for a given profession and city, flagging mismatches that suggest inflated or fabricated income claims.
Loan Stacking Detection
By analyzing bureau data and cross-lender signals, AI can detect when an applicant has taken out multiple loans across different lenders in a short window — a common precursor to over-leveraging and default — even when each individual application looks clean.
Organized Fraud Rings and Bust-Out Fraud
Graph analytics uncover clusters of applications that share devices, IP addresses, referral sources, or contact details, exposing coordinated fraud rings that submit many applications designed to build credit history before defaulting all at once (“bust-out” fraud).
Application Fraud in Digital Lending Apps
For lenders operating fully digital, app-based lending journeys, behavioral biometrics and device fingerprinting detect bots, emulators, and automation scripts used to submit fraudulent applications at scale.
Insider and Collusion Fraud
AI monitoring extends internally as well, flagging unusual approval patterns by specific loan officers or branches — such as an abnormally high approval rate for a particular agent — that may indicate collusion with fraudulent applicants.
Post-Disbursement and Ongoing Monitoring
Fraud detection doesn’t end at approval. AI models continue to monitor repayment behavior, transaction patterns, and account activity after disbursement, flagging early warning signs of default or fraud that only become visible once the loan is live.
Implementation Best Practices for Lenders
Deploying AI fraud detection successfully requires more than plugging in a model. Data quality is foundational — models are only as good as the historical data they’re trained on, so lenders need clean, well-labeled records of both confirmed fraud and genuine applications to train effective systems. Many lenders underestimate how much time this step takes, but skipping it typically produces a model that looks accurate in testing and performs poorly once it meets real, messy production data.
Explainability should be treated as a requirement, not an afterthought. Regulators, auditors, and credit teams all need to understand why a model flagged a particular case, which means building explainability into the system from the start rather than bolting it on later.
Bias and fairness testing matters just as much. Because AI models learn from historical data, they can inadvertently learn and perpetuate historical biases in lending decisions. Regular fairness audits help ensure fraud models don’t disproportionately flag applicants based on protected characteristics or proxies for them.
Integration with existing systems is equally important. Fraud detection delivers the most value when it’s embedded directly into the Loan Origination System (LOS) and Loan Management System (LMS) rather than run as a separate, disconnected check — allowing risk scores to inform underwriting decisions in real time rather than after the fact.
Finally, lenders in India should ensure their fraud detection framework aligns with RBI guidelines on digital lending, KYC/AML norms, and data protection requirements, building compliance into the model governance process from day one rather than retrofitting it later.
The Future of AI Fraud Detection in Lending
As generative AI matures, it introduces new fraud risks alongside its benefits — deepfake videos and voice clones are already being used to attempt identity spoofing during video KYC, pushing fraud detection systems to add liveness detection and deepfake-aware verification as standard components. Lenders that treat this as a future problem rather than a current one risk being caught off guard, since the tools needed to generate convincing synthetic media are already widely accessible.
At the same time, techniques like federated learning are allowing lenders and even competing institutions to collaboratively improve fraud models without directly sharing sensitive customer data, while real-time, API-first fraud engines are becoming the norm for instant digital lending products where every second of latency affects conversion.
For lenders, the direction is clear: fraud detection is moving from a periodic, rule-based checkpoint to a continuous, AI-driven layer woven through the entire loan lifecycle — from first application to final repayment.
Fraud in lending is not going away, and as digital lending volumes grow, neither is the pressure on lenders to catch it earlier and more accurately. AI fraud detection gives banks and NBFCs the tools to move beyond static rules — combining machine learning, document forensics, behavioral analytics, and graph-based network analysis into a system that adapts as fast as fraud tactics evolve. The lenders that adopt this approach early are not just reducing losses; they are building a durable underwriting advantage that compounds as their models learn from every new application they process.
For lenders building or upgrading their Loan Management System, embedding AI-driven fraud detection isn’t just about reducing losses — it’s about approving good borrowers faster, cutting operational overhead, and staying ahead of increasingly sophisticated fraud rings. Platforms like Roopya are built with exactly this shift in mind, helping banks and NBFCs bring intelligent, real-time fraud detection into their core lending workflows.
Frequently Asked Questions (FAQ)
Q: What is AI fraud detection in lending?
A: AI fraud detection in lending refers to the use of machine learning, deep learning, and related technologies to identify fraudulent loan applications, forged documents, and suspicious account activity in real time, replacing or supplementing traditional rule-based checks.
Q: How is AI different from traditional rule-based fraud detection?
A: Rule-based systems rely on fixed conditions that fraudsters can learn to avoid, while AI models learn patterns from historical data, adapt to new fraud tactics over time, and evaluate many weak signals together to catch fraud that individual rules would miss.
Q: What types of lending fraud can AI detect?
A: AI can detect identity theft, synthetic identity fraud, document forgery, income and employment fraud, loan stacking, organized fraud rings, bust-out fraud, and post-disbursement transaction fraud, among other patterns.
Q: Does AI fraud detection slow down loan approvals?
A: No — AI-based risk scoring typically runs in real time, often within milliseconds, allowing genuine applicants to be approved faster while only a small subset of high-risk cases is routed for manual review.
Q: Is AI fraud detection compliant with RBI and KYC/AML regulations?
A: When implemented with explainable AI techniques, detailed audit trails, and fairness testing, AI fraud detection systems can be designed to align with RBI digital lending guidelines and KYC/AML requirements, though lenders should build compliance into model governance from the outset.
Q: How can banks and NBFCs implement AI fraud detection?
A: Lenders typically implement AI fraud detection by integrating it into their existing Loan Origination System (LOS) and Loan Management System (LMS), using quality historical data to train models, and combining multiple techniques such as machine learning, document forensics, and graph analytics for comprehensive coverage.