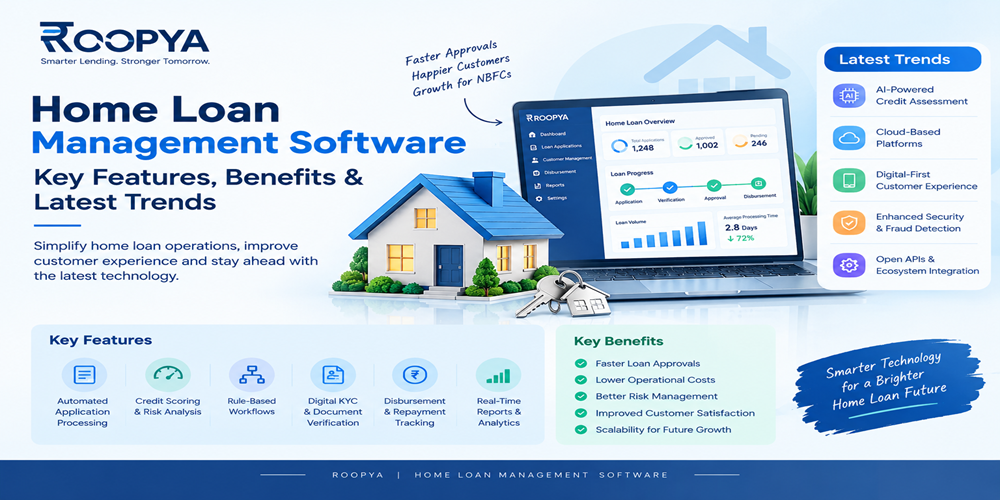
Choosing a loan management system in 2026? See the 12 features every NBFC needs, from RBI compliance to automated collections, and how to evaluate vendors.
Running a lending business in India in 2026 means managing more than repayments. Regulators expect clean audit trails and faster credit bureau reporting. Borrowers expect instant, app-like journeys. Partners expect real-time data over APIs. Boards expect portfolio visibility without waiting for month-end spreadsheets. The system at the centre of all this is your loan management system (LMS).
Many NBFCs still run on a core platform chosen years ago, patched with spreadsheets, manual reconciliations and custom scripts. That setup can work at 500 loans. It rarely survives 50,000. This guide sets out the features a modern LMS must have in 2026, why each matters, and the questions to ask any vendor before you sign. It is written for founders, CTOs, credit heads and operations leaders at NBFCs, banks, microfinance institutions and fintech lenders.
What Is a Loan Management System?
A loan management system is software that manages the post-sanction life of a loan. It creates the loan account, builds the repayment schedule, posts accruals, fees and penalties, collects instalments, handles prepayment and foreclosure, tracks delinquency, classifies assets and closes the account. It also produces the accounting entries and regulatory reports that finance and compliance teams depend on.
It is different from a loan origination system (LOS), which handles the front end: application capture, KYC, underwriting and approval. In practice the two must work as one. Data collected at origination drives servicing, and servicing behaviour feeds back into future credit decisions. A 2026 LMS is therefore judged by how well it connects the whole lending lifecycle, not by how well it runs in isolation.
Why 2026 Raises the Bar for NBFC Technology
Four shifts explain why older systems are struggling.
- Tighter regulation. Digital lending directions, scale-based regulation for NBFCs, key fact statement requirements and faster credit information reporting all demand structured, timestamped data that manual processes cannot reliably produce.
- Rising customer expectations. Borrowers compare your journey with the best consumer apps. Slow disbursal, unclear statements and repeated document requests send them to competitors.
- Partnership lending. Co-lending, business correspondent models and fintech tie-ups need partner-specific rules, splits and reporting inside one platform.
- Asset-quality pressure. Lenders who spot stress early and act quickly protect margins. Those who rely on 90-day buckets alone react too late.
Always check the latest RBI circulars and your own compliance advisers for exact obligations. The features below are designed so that rule changes become configuration changes, not rebuilds.
12 Loan Management System Features Every NBFC Needs
1. Configurable, no-code loan product engine
Your product range will change. You may launch a salary-advance product in one quarter and a small-business term loan in the next. If every new product needs a vendor change request and a six-week release, you will always trail the market. A modern LMS lets business teams define interest methods (flat, reducing balance, daily accrual), tenures, fee structures, moratoria, grace periods, penal charges and prepayment rules through configuration screens.
Look for versioning, so changes to a product do not alter existing loans unless you intend them to, and for the ability to run many products from one instance. Roopya, for example, positions a library of 20+ pre-configured loan products on a no-code foundation so teams can launch by configuring rather than coding.
2. Seamless digital onboarding and KYC
Servicing begins with clean data. The LMS should receive applicant, KYC, bank and collateral records directly from the origination flow, with no re-keying. Native support for Aadhaar-based and CKYC verification, PAN validation, bank account verification, e-sign and e-mandate registration removes the most common causes of drop-off and downstream errors.
The test is simple: can a verified borrower go from approval to a registered repayment mandate without leaving the journey? If not, expect manual follow-ups, delays and higher cost per loan.
3. Rules-based and AI-assisted underwriting
Credit policy should live in a business rule engine, not in an analyst’s head. A strong platform lets credit teams set eligibility rules, scorecards, bureau thresholds and income or FOIR limits, then apply them consistently to every application. It should also support policy overrides with maker-checker approval and a recorded reason.
AI adds value in specific places: reading bank statements and income documents, flagging mismatched details, detecting suspicious patterns, and ranking applications for manual review. Treat it as decision support. Insist on explainability, so you can tell a customer or an auditor why a loan was approved or declined.
4. Accurate loan accounting and schedule management
This is the engine room. The LMS must generate schedules for EMI, bullet, step-up, step-down, balloon and irregular structures. It must post interest accruals daily, apply payments in the correct order (charges, penal interest, interest, principal), and recalculate when something changes: part-payment, rate reset, tenure change, restructuring, moratorium or foreclosure.
Ask for a live demonstration of difficult cases, such as a part-payment on a floating-rate loan after a missed instalment. Mistakes here create customer disputes and audit findings. Also check that the system generates accounting entries that integrate with your general ledger, so finance does not rebuild numbers by hand.
5. Payment automation and real-time reconciliation
Collections efficiency starts with how easily a borrower can pay. Your LMS should support e-NACH and UPI AutoPay mandates, payment links, QR codes, net banking, cards and wallets, plus branch or agent cash receipts with proper receipting. It should handle mandate presentation cycles, bounce reasons and re-presentation rules automatically.
Equally important is reconciliation. Payments arriving in your bank account should be matched to loan accounts automatically, with exceptions queued for review. Teams that reconcile manually often discover mismatches weeks late, which distorts delinquency numbers and frustrates customers who have already paid.
6. Built-in digital lending compliance
Compliance should be part of the workflow, not a spreadsheet beside it. For digital lending, expect to need a key fact statement with the annual percentage rate, a cooling-off or look-up period where applicable, disbursal directly into the borrower’s bank account, clear disclosure of lending service providers, a grievance redressal mechanism, and data-handling that respects consent and storage limits.
Your LMS should store every disclosure, consent and communication with a timestamp, so you can reproduce what a customer was shown on a given date. Configurable templates for sanction letters, statements, no-dues certificates and foreclosure letters further reduce errors. Confirm that the vendor tracks regulatory changes and ships updates as part of the service.
7. Credit bureau reporting and asset classification
Bureau reporting now runs on shorter cycles, and data quality affects both your own credit decisions and your borrowers’ scores. The LMS should generate bureau files in the required formats, validate them before submission, and track rejections for correction.
It should also handle days-past-due calculation, standard, sub-standard and doubtful classification, provisioning, and, where applicable, expected credit loss computation under Ind AS. Automatic upgrades and downgrades on payment or restructuring events spare finance teams from month-end fire drills and give auditors a repeatable method.
8. Workflow-driven collections and recovery
Collections is where margins are won or lost. A capable LMS includes a collections module that segments accounts by days past due, ticket size, risk score and contact history, then triggers the right action: SMS, WhatsApp or email reminders before the due date, IVR or tele-calling queues after it, field visit assignments, and legal notice generation for later stages.
Look for promise-to-pay tracking, agent productivity dashboards, geo-tagged field visits, call and message logs, settlement approval workflows and compliance with fair-practice rules on contact timing and conduct. The aim is to prioritise effort where it recovers most money, and to treat borrowers respectfully while doing so.
9. Early warning system and portfolio monitoring
By the time an account is 30 days overdue, you are already late. An early warning system looks for behaviour that predicts trouble: a first-time late payment, a mandate bounce, falling bureau scores, rising utilisation, changes in cash-flow patterns, or stress in a particular geography, employer or sector.
Useful systems score every account, raise alerts to the right owner, and suggest actions such as a friendly reminder, a restructuring conversation or a limit freeze. Tie alerts to measurable outcomes, such as how many flagged accounts roll into higher delinquency buckets with and without intervention. That is how you prove the system pays for itself.
10. Co-lending and partner management
Co-lending and sourcing partnerships are now mainstream for NBFCs. Your LMS should handle the commercial logic natively: share of each loan between lenders, differing interest rates for each party, blended customer rates, partner-wise fees, settlement cycles, and separate ledgers and reports for each partner.
It should also support default loss guarantee tracking where such arrangements apply, partner-level dashboards, and secure data sharing. If co-lending is handled in spreadsheets today, you carry operational risk that grows with every new partner.
11. API-first architecture and ready integrations
No LMS lives alone. It must exchange data with your LOS, mobile app, CRM, payment gateways, banks, bureaus, KYC providers, account aggregators, accounting software and data warehouse. An API-first design with clean documentation, webhooks for events and sandbox environments shortens every integration.
Pre-built connectors matter just as much. A platform that already integrates with hundreds of third-party services saves months of project time. Roopya lists 300+ pre-integrated APIs, and any vendor you assess should be able to show you which of your required integrations are ready today versus which need custom work.
12. Real-time analytics, MIS and audit-ready reporting
Leaders need answers without waiting for an analyst. Core views include disbursement and collection trends, portfolio at risk by bucket, roll rates, vintage curves, collection efficiency, yield, cost of acquisition and branch or partner performance. Drill-down from a portfolio total to the individual account is essential.
For compliance, the system should offer scheduled regulatory and board reports, role-based access, maker-checker controls and a tamper-evident audit log of every change. Security fundamentals such as encryption, single sign-on, data residency in India, regular penetration testing and recognised certifications such as ISO 27001 and SOC 2 should be confirmed in writing.
How to Evaluate an LMS Vendor in 2026
A feature checklist is necessary but not enough. Use the following criteria to separate strong platforms from impressive demos.
- Time to go live. Ask for a realistic plan with named milestones. Modern cloud platforms can go live in days or weeks for standard products, while complex migrations take longer. Be wary of anything vague.
- Total cost of ownership. Compare licence fees, per-loan or usage charges, implementation costs, change-request fees, hosting and support. Usage-based pricing can lower upfront risk for growing lenders.
- Ask for proof of performance at your projected volume, including month-end batch jobs and peak collection days.
- Configurability versus customisation. Configuration is faster and safer to upgrade. Heavy customisation creates a fork you must maintain forever.
- Regulatory responsiveness. Ask how quickly the vendor shipped updates after the last major circular.
- Speak with at least two lenders of similar size and product type, and ask what went wrong during implementation, not just what went well.
- Exit and data ownership. Confirm you can export your complete data in standard formats at any time.
Common Mistakes NBFCs Make When Choosing an LMS
- Buying for today’s product only. A system that handles one loan type well but cannot add another without vendor work will hold you back within a year.
- Ignoring collections. Many teams spend months on origination and treat collections as an afterthought, even though recovery performance drives profitability.
- Underestimating data migration. Historic loan data is often messy. Plan time for cleansing, mapping and parallel runs.
- Skipping user training. The best software fails if operations, credit and collections teams are not confident using it.
- Choosing on price alone. The cheapest licence can become the most expensive system once change requests and manual workarounds are counted.
A Practical Implementation Roadmap
Even the best platform delivers little without a disciplined rollout. A sensible sequence for most NBFCs looks like this:
- Define scope. List your products, partners, integrations and reports. Mark what is essential for day one and what can follow in a second phase.
- Map your policies. Document interest rules, charge structures, collection strategies and approval limits so they can be configured faithfully.
- Clean and migrate data. Reconcile balances, fix customer records and run a trial migration before the real one.
- Run in parallel. Operate old and new systems side by side for at least one full billing cycle and compare accruals, collections and reports.
- Train every team. Include credit, operations, collections, finance and compliance, with role-based sessions and simple reference guides.
- Go live in stages. Start with one product or branch, fix issues quickly, then expand.
Metrics to Track After Go-Live
Once the LMS is live, measure whether it delivers. Useful indicators include turnaround time from approval to disbursal, cost to service each loan, collection efficiency, the share of payments reconciled automatically, roll rates between delinquency buckets, bureau file rejection rates and the time taken to produce month-end reports. Track the same numbers before and after migration, so the improvement is visible to your board and your team.
Review them monthly and refine rules in response. A configurable platform rewards this habit: a small change to a reminder schedule or an eligibility threshold can be tested in days and rolled out widely if it works, without waiting for a vendor release.
How Roopya Approaches the Modern LMS
Roopya is built as a unified, no-code lending infrastructure covering origination, loan management, collections, early warning and analytics on one platform. For NBFCs, banks, MFIs and loan service providers, that means one data model from application to closure, an AI-enhanced business rule engine that credit and operations teams can change themselves, and compliance and reporting built into the workflow.
The platform is designed for fast deployment, with a pay-as-you-use model that avoids heavy upfront investment. You can explore the full capability on the Roopya loan management system page, or see how origination fits with servicing on the loan origination platform page.
Conclusion: Choose a System Built for Where Lending Is Going
The best loan management system for an NBFC in 2026 is not the one with the longest feature list. It is the one that lets you launch products quickly, stay compliant as rules evolve, collect efficiently, spot risk early and scale without adding headcount at the same pace as loans.
The cost of waiting is real. Every month on an inflexible system means slower launches, more manual effort, weaker visibility into risk and a heavier compliance burden. Lenders who modernise now also gain a lasting advantage: cleaner data, which improves underwriting, which improves portfolio quality, which lowers funding costs over time. Technology choices made this year will shape how competitive your lending business is for the next five.
Use the twelve features above as your scorecard. Score each vendor honestly, test difficult scenarios in a live demo, and speak with reference customers. If you would like to see how a unified, no-code LMS handles your products, request a demo from Roopya and bring your toughest use case.
Frequently Asked Questions
Publish these on the page under the heading “Frequently Asked Questions”. They match the FAQPage schema in Part 4.
What is a loan management system (LMS)?
A loan management system is software that manages a loan after approval. It builds repayment schedules, posts interest and fees, collects payments, tracks overdue accounts, classifies assets, handles closure and produces accounting and regulatory reports.
What is the difference between an LMS and a loan origination system (LOS)?
A loan origination system handles application capture, KYC, underwriting and approval. A loan management system takes over after sanction, covering disbursal, servicing, collections and closure. Modern lenders prefer both on one platform so data flows without re-entry.
Which features should an NBFC prioritise in a loan management system?
Prioritise a configurable product engine, accurate loan accounting, payment and mandate automation, digital lending compliance, bureau reporting with asset classification, collections workflows, early warning alerts, co-lending support, open APIs and real-time analytics.
Does an LMS help with RBI compliance?
A good LMS supports compliance by storing disclosures and consents with timestamps, generating key fact statements and statutory reports, producing credit bureau files and applying asset classification rules. Final responsibility stays with the lender, so confirm requirements with your compliance team and the latest RBI circulars.
How long does it take to implement a loan management system?
Timelines depend on product complexity, integrations and data migration. Cloud-based, no-code platforms can launch standard products in days or weeks. Complex migrations with many integrations take longer. Ask any vendor for a milestone-based plan.
Can a loan management system support co-lending?
Yes, if it is designed for it. Look for configurable loan splits, separate rates for each lender, partner-wise ledgers and settlements, default loss guarantee tracking and partner dashboards.
How does an LMS improve collections?
It segments overdue accounts by risk and delinquency stage, automates reminders across SMS, WhatsApp and email, assigns calling and field tasks, tracks promises to pay and reports agent performance. Early warning alerts help teams act before accounts become seriously overdue.
Is a cloud-based LMS secure enough for a regulated lender?
It can be, provided the vendor offers encryption, role-based access, audit logs, regular security testing, recognised certifications and data hosting that meets Indian regulatory expectations. Verify these in writing and review the vendor’s security documentation before signing.