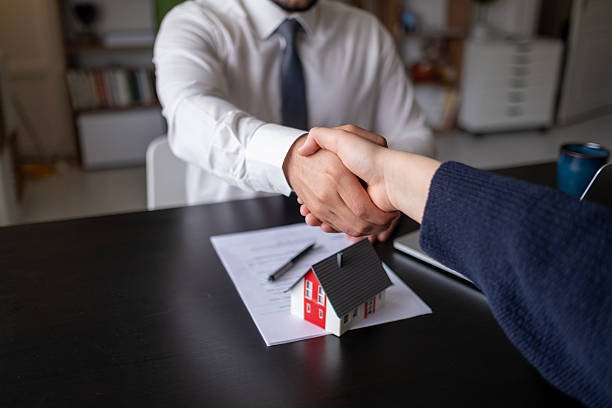
Real estate agents shake hands after the signing of the contract agreement is complete.
Buying property is a big financial decision. Whether you’re planning to purchase your first home or thinking about investing in a rental property, the financing part can get confusing pretty quickly. There are different loan options, interest rates, fees, and eligibility requirements to understand. And honestly, choosing the wrong financing option can cost you more than you expect.
That’s why many buyers start by searching for a mortgage broker. They want someone who can explain their options, compare available loans, and help them understand what makes sense for their situation. For real estate investors, the process can be a little different because investment properties often come with different lending requirements than owner-occupied homes.
If you’re exploring investment property loans, it helps to understand how mortgage brokers work, what lenders look for, and how to prepare before applying. A little research at the beginning can save time and help you avoid unpleasant surprises later.
What Is a Mortgage Broker?
A mortgage broker is a professional who helps borrowers explore mortgage options from lenders they work with. Instead of approaching every lender separately, you may be able to work with a broker who gathers information about your financial situation and identifies potential loan programs.
Mortgage brokers can help explain interest rates, repayment terms, down payment requirements, and application procedures. They may also help organize paperwork and communicate with lenders throughout the application process.
However, a mortgage broker does not automatically provide access to every loan available in the market. The lenders and products they can offer depend on their relationships, licensing, and business arrangements.
It is also important to understand that a broker is not the same as a bank. A bank or other direct lender may evaluate your application and provide financing through its own lending programs. A broker typically helps connect borrowers with lenders, while the lender makes the final decision about approval and loan terms.
Both approaches can be useful. The better choice depends on the type of property you want to purchase, your financial position, and how much guidance you need.
Understanding Investment Property Loans
Investment property loans are financing options used to purchase or refinance real estate that is primarily intended to generate income or provide investment returns.
For example, you might purchase a house and rent it to tenants. You could also invest in a residential property that you plan to hold for several years before selling. In both cases, the property serves a different purpose from a home you intend to occupy yourself.
Because rental properties involve different financial risks, lenders may apply different requirements to investment property mortgages. They may look closely at your credit history, income, existing debts, available cash reserves, and the property’s expected rental income.
Down payment requirements may also be higher than those for some owner-occupied mortgage programs. The exact amount depends on the lender, property type, loan structure, and borrower qualifications.
The important thing is to avoid assuming that the financing process will be identical to buying your own home. It often isn’t.
Before making an offer on an investment property, estimate the full cost of ownership. Mortgage payments are only one part of the picture. Property taxes, insurance, repairs, vacancies, maintenance, and property management can all affect your returns.
How a Mortgage Broker Can Help Real Estate Investors
Real estate investors often have different priorities from traditional homebuyers. They may be comparing rental income, evaluating several properties, or planning to build a portfolio over time.
A mortgage broker may help investors explore available financing options based on their goals. For instance, someone buying a single rental home may need a different loan structure than an investor purchasing several units.
A broker can also help explain how lenders assess investment properties. Some lenders place considerable weight on the borrower’s personal income and credit profile. Others may consider projected rental income or use different underwriting methods, depending on the loan program.
Here are a few areas where a broker may provide assistance:
- Loan comparisons: Reviewing available interest rates, fees, repayment terms, and down payment requirements.
- Application preparation: Helping borrowers understand which financial documents lenders may request.
- Investment planning: Discussing financing structures that may fit the intended property purchase.
- Lender communication: Helping borrowers navigate questions and documentation during the application process.
Still, working with a broker does not guarantee approval or the lowest rate. You should ask how the broker is compensated, which lenders they work with, and whether any fees apply directly to you.
Compare the proposed terms yourself, too. A professional can guide you, but you are the one who will be responsible for the loan.
Mortgage Broker or Bank: Which Option Makes More Sense?
There isn’t one answer that works for everyone. Both mortgage brokers and banks can be useful, depending on your financing needs.
A mortgage broker may be helpful if you want to compare products from multiple lenders without submitting separate inquiries to each one. A broker may also know which lenders offer programs suited to particular borrower profiles or property types.
A bank, on the other hand, may offer direct access to its own lending programs and banking services. Depending on the institution, you may be able to discuss real estate financing alongside checking accounts, savings, and other financial needs.
Working directly with a lender can also make it easier to understand who is responsible for underwriting and making the final lending decision.
When comparing the two, look beyond convenience. Ask for a clear explanation of the interest rate, annual percentage rate (APR), closing costs, loan term, and any prepayment restrictions.
Also, check whether the quoted rate is fixed or adjustable. A fixed-rate loan generally keeps the interest rate unchanged for the agreed term, while an adjustable-rate loan may change according to its terms.
Don’t rush into a decision just because one option sounds easier. The details matter more than the sales pitch.
What Lenders Look for When Approving Investment Property Loans
Lenders want to understand whether you can repay the money you borrow. For investment property loans, they may also assess the property’s potential to generate income and cover its expenses.
Your credit history is one important factor. A stronger credit profile may help you qualify for more favorable terms, although approval depends on several factors rather than credit score alone.
Your debt-to-income ratio can matter as well. This measures your monthly debt payments against your gross monthly income. Existing mortgages, car payments, credit card obligations, and other debts may affect how much additional borrowing a lender considers manageable.
Cash reserves are another consideration. An investment property can sit vacant for a few weeks or need an expensive repair at the worst possible time. Having accessible savings can help you manage those situations without falling behind on payments.
Lenders may also evaluate the property’s value, condition, rental potential, and intended use. Depending on the loan, they may request a property appraisal, rental information, leases, or other supporting documents.
Before applying, gather your income records, asset statements, existing debt information, and details about the property. Ask the lender for its document checklist so you know what to prepare.
How to Calculate Whether an Investment Property Is Worth Buying
A property can look profitable on paper but perform very differently in real life. That’s why you should run the numbers before committing to a purchase.
Start by estimating the monthly rental income. Then subtract expected operating expenses, including property taxes, insurance, maintenance, management fees, and an allowance for vacancy periods.
Next, account for your mortgage payment. The amount left over gives you a clearer picture of the property’s potential cash flow, although actual results can change as expenses and rental conditions change.
For example, imagine a property that rents for $2,000 per month. That does not mean you have $2,000 available to spend. You still need to cover operating costs and loan payments, along with unexpected expenses.
It is also worth considering how much money you need upfront. The down payment, closing costs, initial repairs, and furnishing expenses can reduce the cash you have available for other investments.
Think about your longer-term goal, too. Are you looking for monthly income, property appreciation, or a combination of both? Each strategy comes with different risks.
Be realistic about rental demand and avoid relying entirely on optimistic projections. A conservative estimate is usually more useful than a perfect-looking spreadsheet.
Common Mistakes to Avoid When Financing an Investment Property
One common mistake is focusing only on the interest rate. A lower rate may look attractive, but higher fees or less favorable loan conditions could change the overall cost.
Another mistake is underestimating maintenance. Roof repairs, plumbing issues, appliance replacements, and other problems can quickly eat into rental income. Keep an emergency reserve rather than assuming everything will go according to plan.
Some buyers also borrow close to their maximum approved amount without considering how they would handle a vacancy or a change in income. Being approved for a particular loan amount doesn’t mean you should borrow the full amount.
Finally, don’t skip the paperwork. Review the loan agreement, payment schedule, closing costs, and any conditions that could affect your ability to refinance or sell the property later.
Ask questions before signing. If a term is unclear, get it explained.
Find the Right Financing Approach for Your Property Goals
Choosing between a mortgage broker and a bank starts with understanding what you want to achieve. If you are buying a rental property, compare financing options based on the property’s numbers, your financial position, and the risks you can reasonably manage.
A mortgage broker may help you explore products from different lenders. A bank may provide direct lending options and broader banking services. Either route can be worth considering, provided you understand the terms and compare the complete cost of borrowing.
SouthStar Bank offers banking and lending services for customers exploring their financial options. If you’re planning a real estate purchase or researching financing for your next investment property loans, reviewing the available services can be a useful first step.
Frequently Asked Questions
1. What does a mortgage broker do?
A mortgage broker helps borrowers explore mortgage options from lenders they work with. They may compare available loan products, explain requirements, and assist with the application process. The lender makes the final decision on approval.
2. Are investment property loans different from regular home mortgages?
Yes. Investment property loans finance properties intended primarily for rental income or investment purposes. They may involve different down payment requirements, interest rates, reserve requirements, and qualification standards than mortgages for owner-occupied homes.
3. Can first-time investors qualify for investment property loans?
First-time investors may qualify, depending on their credit history, income, savings, existing debts, and the property’s details. Requirements vary by lender and loan program. Reviewing your finances and getting an initial assessment can help you understand your options.
4. Should I use a mortgage broker or approach a bank directly?
It depends on your needs. A mortgage broker may help you compare options across participating lenders, while a bank can explain its own lending products directly. Compare rates, fees, loan terms, service, and eligibility requirements before deciding.