What Mortgage Note Buyers Check Before Purchasing a Note
Selling a mortgage note can provide a note holder with an opportunity to convert future payments into immediate capital. However, before completing a transaction.
Mortgage Note Buyers generally review several aspects of the loan, borrower, property, and supporting documentation. Understanding this evaluation process can help note holders prepare their files and help investors conduct more organized due diligence.
A mortgage note represents a borrower’s promise to repay a loan secured by real estate. Because the property provides collateral, buyers need to understand both the financial characteristics of the loan and the condition of the underlying property records.
Reviewing the Payment History
One of the first areas buyers may examine is the borrower’s payment history. Consistent payments can provide information about the current performance of the loan, while frequent late or missed payments may indicate additional risk.
The timing of any delinquency can also matter. A borrower who recently returned to consistent payments may present a different situation from one who has remained delinquent for an extended period.
For note holders, maintaining accurate servicing records is important because payment history helps buyers understand the actual performance of the asset.
Examining the Property Behind the Note
The property securing the mortgage is another important consideration. Mortgage Note Buyers may review the property’s estimated current value, location, condition, and available market information.
The relationship between the property value and outstanding loan balance can help buyers understand the collateral position. An updated valuation may be useful because property values can change significantly after the original loan was issued.
Buyers may also consider whether the property is occupied, vacant, residential, commercial, or subject to other circumstances that could affect the investment.
Understanding Loan Terms
The financial terms of a mortgage note can influence its attractiveness to a potential buyer. The interest rate, outstanding principal balance, monthly payment, maturity date, and remaining term all contribute to the expected cash flow.
A buyer may compare the note’s interest rate with current market conditions while also considering the level of risk associated with the asset.
For example, two mortgage notes with similar balances may have very different investment characteristics if one has a significantly longer remaining term or a different payment history.
Checking Lien Position
Lien position is another critical part of mortgage note due diligence. A buyer needs to understand where the mortgage stands relative to other recorded interests associated with the property.
A first-lien mortgage generally has priority over junior liens, subject to applicable law and the specific circumstances of the property. A junior-lien investment can involve additional considerations because another creditor may have priority.
Public-record research can help verify the recorded mortgage, ownership information, judgments, tax-related matters, and other liens.
Reviewing Title Records
Title research can provide valuable information about the property securing a mortgage note. Buyers may review the ownership history, recorded mortgages, assignments, judgments, easements, and other relevant interests.
A complete title review can help identify discrepancies between the information provided by a seller and what is reflected in public records.
For investors, identifying potential title issues before purchasing a note can provide an opportunity to investigate the issue and determine whether additional professional review is needed.
Evaluating Documentation
Complete documentation can make a mortgage note easier to evaluate. Buyers may request the original promissory note, mortgage or deed of trust, assignments, payment history, closing documents, modifications, and other supporting records.
The assignment history is particularly important because it can help establish how ownership of the note transferred from the original lender to the current holder.
If documentation is incomplete, a buyer may need additional research before determining whether the asset fits their investment requirements.
Performing and Non-Performing Notes
Mortgage Note Buyers may specialize in performing notes, non-performing notes, or both.
Performing notes generally involve borrowers who are making payments according to the loan terms. Buyers may evaluate these assets primarily around expected cash flow, collateral, and loan characteristics.
Non-performing notes involve significant payment delinquency and can require additional analysis. Buyers may consider borrower communication, potential modification options, foreclosure status, property value, legal requirements, and recovery scenarios.
The appropriate investment depends on the buyer’s strategy and the specific characteristics of the note.
Why Due Diligence Is Important
Mortgage note transactions involve multiple sources of information. Loan documents, servicing records, title records, public records, property information, and tax records may all need to be reviewed.
A structured due diligence process helps investors compare this information and identify inconsistencies.
For example, a loan file might indicate one lien position while public records reveal another recorded interest. Similarly, the property’s current value may differ from an older valuation used during the original loan transaction.
These differences do not automatically make a note unsuitable, but they can create questions that should be addressed before the transaction is completed.
How scalanceglobal Supports Mortgage Note Investors
scalanceglobal provides title, lien, collateral, and public-record research designed to support mortgage note transactions. Its services include lien position verification, chain-of-title and assignment review, loan-data reconciliation, tax and insurance checks, collateral file review, and payment-history reconciliation.
For investors evaluating larger portfolios, organized research can also help identify exceptions that require additional asset-level investigation.
This type of support allows investment teams to focus on reviewing the information and determining which assets require additional attention. Scalance Global’s services are designed to complement, rather than replace, appropriate legal, tax, financial, and investment advice.
Preparing Before Selling a Mortgage Note
Note holders can make the evaluation process more efficient by preparing their documentation before approaching potential buyers. Organizing the payment history, original loan documents, assignments, title information, tax records, insurance information, and modification documents can give buyers a clearer view of the asset.
It can also be useful to identify missing documents or unresolved issues before beginning negotiations. Addressing potential questions early may help reduce delays during the buyer’s due diligence process.
While documentation does not guarantee a particular purchase price, a well-organized file can make the asset easier to evaluate.
Building a Better Mortgage Note Investment Process
Investors can benefit from establishing a consistent process for reviewing mortgage notes. Rather than evaluating each asset based only on its purchase price or remaining balance, buyers can consider the complete investment profile.
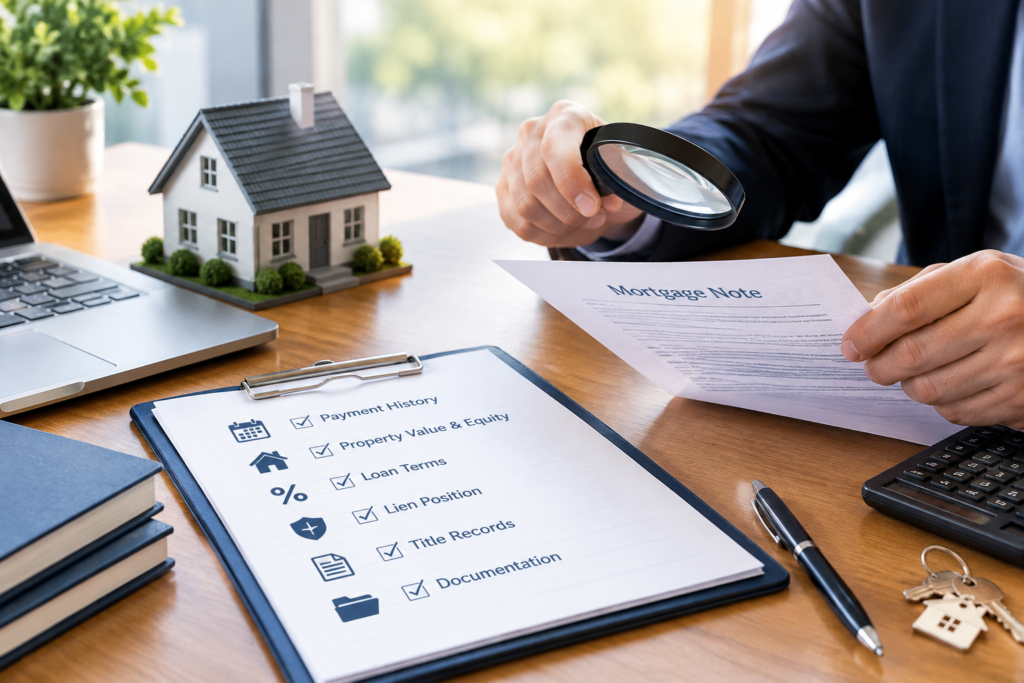
Payment performance, collateral value, LTV, lien position, interest rate, remaining term, title condition, documentation, taxes, insurance, and potential servicing or legal costs can all contribute to the overall evaluation.
For portfolio acquisitions, the same principles can be applied across multiple assets while allowing additional research for files with specific exceptions.
Conclusion
Mortgage Note Buyers typically look beyond the outstanding balance when evaluating a potential investment. They may review payment history, property value, loan terms, lien position, title records, documentation, and the overall condition of the asset.
For note holders, understanding these factors can make it easier to prepare a mortgage note for evaluation. For investors, a structured due diligence process can help identify important questions before capital is committed.
With its focus on title, lien, collateral, and public-record research, scalanceglobal supports mortgage note investors and note holders throughout the due diligence process. By organizing important information and identifying potential exceptions, investors can develop a clearer understanding of the assets they are considering.
Whether the transaction involves a single mortgage note or a larger portfolio, careful research remains an important part of evaluating real estate-backed debt.