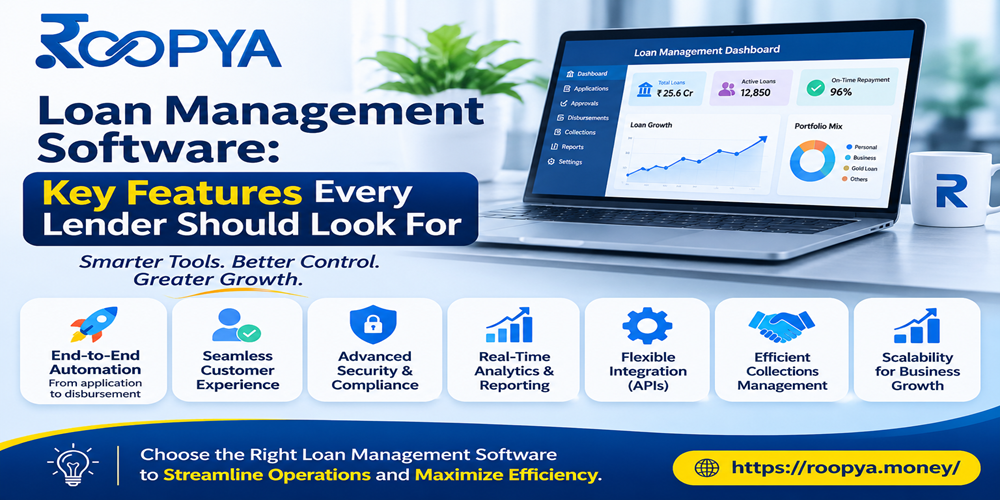
Choosing loan management software? Explore the key features every lender needs, from digital origination and BRE to compliance, analytics and collections
Choosing loan management software is one of the most consequential technology decisions a lender will make. The system you pick shapes how quickly borrowers get approved, how accurately risk is assessed, how reliably repayments are tracked and how confidently you can face an audit. Pick well, and your team spends its time growing the portfolio. Pick poorly, and you end up with spreadsheets, manual workarounds and a growing list of integrations that never quite work.
This guide is written for NBFCs, banks, fintechs, lending service providers (LSPs) and digital lending startups that are evaluating or replacing a loan management system (LMS). It explains what the software should actually do, the twelve features that matter most, how to test them during a demo, and the mistakes that cause lenders to regret a purchase 12 months later.
What Is Loan Management Software?
Loan management software is a platform that automates and tracks the full life of a loan: application, verification, underwriting, approval, documentation, disbursal, servicing, collections and closure. Instead of passing a file between teams and systems, every stage lives in one workflow with a single source of truth for borrower and loan data.
The terms can be confusing, so here is a practical distinction. A loan origination system (LOS) handles everything up to disbursal. A loan management system (LMS) handles everything after it, such as repayment schedules, interest accrual and collections. Many modern platforms combine both, and some, like lending-as-a-service (LaaS) platforms, add lender connectivity and analytics on top. When you compare vendors, always ask which part of the lifecycle each product genuinely covers.
Why the Right Features Matter More Than the Price Tag
It is tempting to shortlist software by licence cost. In lending, however, the expensive mistakes are rarely the subscription fee. They are slow turnaround times that push borrowers to a competitor, inconsistent credit decisions that raise defaults, missed regulatory requirements that invite penalties, and manual reconciliation that quietly eats your operations budget.
A feature-first evaluation keeps the focus on outcomes: faster approvals, lower cost per loan, cleaner books and better risk control. The sections below walk through the capabilities that most directly influence those outcomes.
12 Key Features Every Lender Should Look For
1. Digital Loan Origination and Borrower Onboarding
The borrower’s first experience with your brand is the application. Good software lets applicants apply on web or mobile, upload documents, complete e-KYC and e-sign agreements without visiting a branch or emailing PDFs. Look for configurable application forms, document capture with basic validation, duplicate-application checks and the ability to save and resume a half-finished application.
Equally important is how the system handles leads from different sources. If you receive applications from your own app, from DSAs, from marketplaces and from channel partners, the platform should accept them all through one pipeline and tag each with its source so you can measure which channels actually produce good loans.
2. A Configurable Business Rules Engine (BRE)
A business rules engine is the brain of a lending platform. It lets you define eligibility, pricing, limits and routing logic without asking a developer to change code each time your credit policy shifts. A strong BRE should let your credit team create rules based on age, income, bureau score, location, employment type, product and more, then test and version those rules before they go live.
Ask vendors whether rules can be changed by non-technical users, whether there is a sandbox for testing, and whether every decision is logged with the exact rule that triggered it. That last point is critical for explainability. When a regulator, auditor or customer asks why a loan was declined, you need a clear answer, not a shrug.
3. Automated Credit Decisioning and Underwriting Support
Manual underwriting does not scale. The software should pull data from credit bureaus, bank statement analysers, income verification tools, KYC providers and fraud-detection services, then feed it into your decisioning logic. Straight-through processing for clearly good or clearly bad applications frees your underwriters to focus on borderline cases where human judgement adds value.
Check how easily new data sources can be plugged in. Alternative data, such as GST returns, account aggregator data or utility payments, is increasingly useful for thin-file borrowers, and you do not want to wait months for a vendor to add each connector.
4. Multi-Lender Connectivity and Intelligent Routing
If you are a lending service provider, aggregator or fintech that does not lend purely from its own balance sheet, multi-lender connectivity is a defining feature. Instead of building a separate integration for every bank or NBFC, a good platform exposes a single integration layer through which applications can be matched and pushed to multiple lenders.
The most valuable systems go a step further and use customer profiling to recommend the lender most likely to approve a given applicant, rather than blasting the same application to everyone. This improves disbursal ratios and protects the borrower’s credit score from unnecessary hard enquiries. For example, Roopya’s lending infrastructure connects with 25+ lenders through APIs and uses 25+ customer data points to match each borrower with a suitable lender.
5. Customisable Journey Builder and Workflow Automation
Every lending product has a different journey. A small-ticket personal loan may need five steps, while a business loan may need document collection, site verification and committee approval. Rigid, one-size-fits-all workflows force you to bend your process around the software.
A no-code or low-code journey builder lets you design screens, sequence steps, add conditional branches and trigger notifications. It also lets you test small changes, such as moving the consent screen or removing an optional field, and see how they affect completion rates. This is one of the fastest ways to improve conversion without engineering effort.
6. Automated Disbursal and Payment Integration
Once a loan is approved, money has to move quickly and accurately. Look for integrations with payment gateways and banking rails for disbursal through methods such as NEFT, IMPS and UPI, along with automatic status updates and failure handling. Under RBI’s digital lending guidelines, disbursals are expected to go directly into the borrower’s bank account, so your software should support that flow and keep a clear audit record.
On the collection side, the system should support e-NACH or e-mandate registration, UPI AutoPay, payment links and virtual accounts, and it should reconcile incoming payments automatically against the right loan and instalment. Manual reconciliation is one of the biggest hidden costs in lending operations.
7. Loan Servicing and Repayment Schedule Management
This is the core of a traditional LMS. The software must calculate interest and fees correctly, generate amortisation schedules, handle part-payments, prepayments, foreclosure, restructuring and charge-offs, and show borrowers an accurate outstanding balance at any moment.
Test the edge cases during a demo: a payment made one day late, a prepayment in the middle of a cycle, a change in interest rate for a floating-rate product, a bounced instalment. Software that handles the happy path but stumbles on these will create reconciliation headaches and customer disputes.
8. Collections and Recovery Management
Delinquency starts small and becomes expensive quickly. Look for automated reminders through SMS, WhatsApp, email and IVR before and after the due date, along with bucket-wise segmentation (for example, 1–30, 31–60 and 61–90 days past due), agent allocation, promise-to-pay tracking and field collection workflows.
The best collection modules support compliant communication: respecting contact windows, logging every interaction and escalating to legal workflows only when needed. Treating borrowers respectfully is not only the right approach but also reduces complaints and regulatory risk.
9. Analytics, Dashboards and AI-Driven Reporting
You cannot improve what you cannot see. Your platform should offer real-time dashboards covering application funnel conversion, approval rates, turnaround time, disbursal volumes, portfolio at risk, collection efficiency and lender-wise performance. Drill-down capability matters: a headline number is useful, but you also need to see which channel, product or region is driving it.
Increasingly, platforms add AI-assisted reporting that surfaces anomalies, predicts delinquency or highlights growth opportunities. Treat these as helpful accelerators, but ask to see how the models are validated and whether your team can understand and override their outputs.
10. Security, Compliance and Audit Trails
Lending involves some of the most sensitive personal and financial data there is. At a minimum, look for encryption in transit and at rest, role-based access control, multi-factor authentication, detailed activity logs and regular security testing. Ask about certifications such as ISO 27001 or SOC 2, and where your data will be hosted, since Indian regulators have clear expectations about data localisation for payment and financial data.
On the compliance side, the software should help you follow RBI digital lending guidelines, including borrower consent capture, a Key Fact Statement (KFS) before the loan is accepted, transparent disclosure of the annual percentage rate and fees, and grievance redressal workflows. It should also support obligations under India’s Digital Personal Data Protection Act, 2023. Remember that software supports compliance but does not replace your own legal review, so confirm requirements with your compliance team.
11. Open APIs and Easy Integrations
No LMS works alone. It will need to talk to your accounting system, CRM, bureaus, payment partners, collection tools and data warehouse. Well-documented REST APIs, webhooks, sandbox environments and clear versioning policies make these integrations faster and safer.
Ask how long a typical integration takes, who builds it, and what happens when a third-party provider changes its API. A vendor that has already integrated with the partners you use will save weeks of effort.
12. Scalability, Multi-Product Support and Reliable Support
The platform that suits 500 loans a month may struggle at 50,000. Ask for evidence of performance under load, uptime commitments and disaster-recovery plans. Also check that the system can support multiple loan products, branches, partners and tenants from a single installation, since most lenders expand beyond their first product.
Finally, consider the human side: implementation support, training, documentation and response times when something breaks at month-end. Good support is a feature, even though it never appears on a product page.
How to Evaluate Loan Management Software: A Practical Checklist
Feature lists look similar across vendors, so the difference lies in how deeply each capability is implemented. Use the following approach to cut through marketing language.
- Define your lending model first: own balance sheet, co-lending, lending service provider or marketplace. Each needs a different emphasis.
- Map your current process end to end and mark the manual steps that cause the most delay or error.
- Ask for a live demo using your own sample scenarios, not a polished script.
- Request customer references in a similar segment and size, and ask them about post-launch support.
- Check the total cost of ownership, including implementation, integration, per-loan or per-user fees and change requests.
- Review the product roadmap and how the vendor responds to regulatory changes.
- Confirm data ownership, export options and exit terms before signing.
Common Mistakes Lenders Make When Buying an LMS
Even careful buyers fall into a few predictable traps. The first is buying for today’s product only. If you plan to add a new loan type or partner within two years, make sure the platform can handle it without a rebuild. The second is ignoring the borrower experience, because a powerful back office does not help if applicants abandon a clumsy front end.
The third mistake is underestimating integration effort. A platform that looks complete in a demo can still take months to connect with your bureaus, banks and collection partners. The fourth is treating compliance as a one-time checklist rather than an ongoing need. Regulations evolve, so your vendor’s ability to update the product quickly matters as much as its current features.
Where Roopya Fits In
Roopya offers a Lending-as-a-Service (LaaS) infrastructure and analytics platform designed for businesses that want to start or scale a digital lending operation. Rather than only tracking loans after disbursal, it covers the pipeline from application submission through underwriting, credit decisioning, digital document signing, fund transfer and ongoing servicing.
Several capabilities map directly to the features discussed above. Roopya provides an inbuilt, fully customisable customer journey builder, a business rules engine (BRE) that lets lending service providers define and run rules across origination, underwriting and servicing, and API connectivity with 25+ lenders to improve disbursal ratios. It also uses customer profiling to match borrowers with a suitable lender, offers AI-driven reports for decision-making, and supports multiple channel partners so lenders can widen their reach and product range.
If you are evaluating platforms, you can use the checklist above to assess any vendor, including Roopya, against your specific needs. You can learn more about the platform at roopya.money.
Conclusion
The best loan management software is not necessarily the one with the longest feature list. It is the one that fits your lending model, makes good credit decisions repeatable, keeps borrowers moving smoothly through the journey, and gives your team clear visibility and compliance confidence. Start with digital origination, a flexible BRE, automated decisioning, reliable disbursal and servicing, strong collections, meaningful analytics and robust security. Then test each of them against real scenarios from your own business.
Take your time with the evaluation. A few extra weeks of careful comparison can save years of operational friction, and the right platform becomes a foundation you can grow on rather than a constraint you work around.
Frequently Asked Questions (FAQ)
What is loan management software?
Loan management software is a platform that automates the lending lifecycle, including application intake, underwriting, approval, disbursal, repayment tracking, collections and loan closure. It keeps borrower and loan data in one place, reduces manual work and improves accuracy and compliance.
What is the difference between a loan origination system and a loan management system?
A loan origination system (LOS) manages the process up to disbursal, such as applications, KYC and underwriting. A loan management system (LMS) manages the loan after disbursal, including repayment schedules, interest, collections and closure. Many modern platforms combine both in a single product.
Which features are most important in loan management software?
The most important features are digital origination and onboarding, a configurable business rules engine, automated credit decisioning, payment and disbursal integration, loan servicing, collections management, analytics and reporting, security and compliance controls, open APIs, and scalability.
Can small lenders and fintech startups use loan management software?
Yes. Cloud-based and API-first platforms are often priced and configured so that early-stage lenders, NBFCs and fintechs can launch without building their own technology. Look for a platform that can start with one product and scale to more products, partners and volumes later.
How does a business rules engine help in lending?
A business rules engine lets lenders define eligibility, pricing, limits and routing criteria without writing code. It makes credit decisions consistent, speeds up approvals, allows quick policy changes and records the reason for each decision, which helps with audits and explainability.
How does loan management software support regulatory compliance?
It can help by capturing borrower consent, presenting a Key Fact Statement, maintaining audit trails, restricting data access by role, supporting direct disbursal to the borrower’s account and managing grievances. Software supports compliance but does not replace legal advice, so lenders should confirm requirements with their compliance teams.
How long does it take to implement loan management software?
Timelines vary with the number of products, integrations and the amount of customisation required. Simple, configuration-led deployments can go live much faster than complex, multi-product projects. Ask vendors for a realistic plan based on your scope and your existing systems.
What should I ask a vendor before choosing a loan management system?
Ask about supported lending models, rule configuration, integrations with bureaus and payment partners, security certifications, data hosting, uptime, pricing structure, customer references, implementation support, and what happens to your data if you leave.